Many ETFs pay dividends or other distributions to investors. If you own shares of a dividend paying ETF , you may receive income generated by the stocks, bonds, REITs, or other investments held by the fund. However, ETF dividends are not always as simple as a stock dividend. Different ETFs pay at different frequencies, distributions can change, and a high yield does not automatically mean an ETF is a better investment. In this guide, we explain ETF and dividends, how ETF dividend payments work, how often ETFs pay, how to check dividend history, what dividend yield means, and what investors should consider before choosing a dividend ETF.
Also visit: ETF Guides & Analysis
What Are ETF Dividends?
An ETF, or exchange-traded fund, is a basket of investments that trades on a stock exchange. An ETF may hold dozens, hundreds, or even thousands of securities. When the investments inside the ETF generate income, the fund may distribute some of that income to shareholders.
For example, a stock ETF may own companies that pay dividends. The ETF collects those dividends and may pass the income to investors through a distribution. Bond ETFs can work differently. Their distributions may mainly come from interest earned on the bonds they hold. This means an ETF distribution can come from different sources, including:
- Stock dividends
- Bond interest
- REIT income
- Capital gains
- Other investment income
- Return of capital in some cases
Dividend vs. Distribution: Are They the Same?
People often use “dividend” and “distribution” interchangeably, but they are not always exactly the same. A company generally pays a dividend from its earnings or available profits. An ETF can distribute several types of income or gains generated by the securities in its portfolio. That is why ETF distribution is often the more accurate term. For investors, the important question is not only how much an ETF distributes, but where that distribution comes from.
Do ETFs Pay Dividends?
Yes, many ETFs pay dividends or distributions. But not all ETFs pay regular dividends. Whether an ETF distributes income depends largely on what it owns and how the fund is designed.
For example:
- Dividend-focused stock ETFs may distribute stock dividends.
- Bond ETFs may distribute interest income.
- REIT ETFs may distribute income from real estate investments.
- Growth-oriented ETFs may have relatively low distributions.
- Some specialized income ETFs may make very frequent distributions.
So if you are looking for ETFs that pay dividends, check the fund’s distribution history and official fund information instead of assuming every ETF provides regular income.
Do All ETFs Pay Dividends?
No. An ETF can have little or no regular distribution. Some funds focus primarily on growth or assets that generate little current income. The absence of a large dividend does not automatically mean an ETF is a poor investment. Investors should consider total return, not just distributions.
How Do ETF Dividends Work?
The basic process is fairly simple. Suppose an ETF owns 500 stocks. Several of those companies pay dividends to the ETF. The ETF receives that income. After considering fund expenses and other factors, the fund may distribute income to its shareholders.
The simplified process looks like this: Underlying investments → ETF receives income → fund calculates distribution → eligible ETF shareholders receive payment
The exact process depends on the ETF and its investment strategy.
Where Do ETF Dividends Come From?
ETF distributions can come from the underlying securities held by the fund. For a stock ETF, this can include dividends paid by companies. For a bond ETF, distributions may largely reflect interest income from bonds. For some specialized ETFs, distributions can involve other sources. This is why two ETFs with similar-looking yields can have very different risk and return profiles.
What Happens to an ETF Price After a Distribution?
A common beginner question is whether receiving an ETF dividend creates free money. It does not work that way. When a fund makes a distribution, the fund’s assets and NAV are reduced by the amount distributed, all else equal. The market price can also adjust around the distribution.
For example, imagine an ETF trading at $100 and making a $1 distribution. The distribution itself does not magically create an additional $1 of wealth. You would have an investment worth roughly $99 plus the $1 distribution, before considering market movements, taxes, fees, and other factors.
This is one reason total return matters more than simply looking at the distribution amount.
Also Read: SPMO ETF
How Often Do ETFs Pay Dividends?
ETF dividend frequency varies by fund.
Common schedules include:
| Frequency | Description |
|---|---|
| Weekly | Available from some specialized income ETFs |
| Monthly | Common among many income and bond ETFs |
| Quarterly | Common among many stock ETFs |
| Semiannual | Used by some funds |
| Annual | Used by some ETFs |
Always check the specific ETF’s distribution schedule because frequency can change.
Weekly Dividend ETFs
Weekly dividend ETFs are ETFs designed to make distributions on a very frequent schedule. Searches such as “weekly dividend ETF,” “weekly dividend ETFs,” and “ETFs that pay weekly dividends” generally refer to funds offering frequent income distributions.
How Do Weekly Dividend ETFs Work?
The ETF’s distribution strategy determines how income is generated and distributed. A weekly payment does not necessarily mean the fund is generating more income than a monthly or quarterly ETF. The same overall annual income could potentially be divided into more frequent payments.
Are Weekly Dividend ETFs Better?
Not necessarily. Payment frequency and investment quality are different things.
When comparing weekly dividend ETFs, look beyond the advertised yield and examine:
- Total return
- NAV performance
- Distribution history
- Distribution composition
- Expense ratio
- Portfolio holdings
- Investment strategy
- Volatility
- Liquidity
- Bid-ask spread
Risks of Weekly Dividend ETFs
Some high-distribution weekly income strategies can involve more complex techniques, including options or other strategies designed to generate income.
Potential risks can include:
- High volatility
- Limited upside potential
- Distribution reductions
- High fees
- Strategy risk
- Return-of-capital distributions
- Weak long-term total returns
Therefore, weekly income does not automatically mean better investment performance.
Monthly Dividend ETFs
Monthly dividend ETFs distribute income every month rather than every quarter or less frequently. They can be attractive to investors who prefer more regular cash flow.
Common types of monthly income ETFs include:
- Bond ETFs
- Covered-call ETFs
- Preferred-stock ETFs
- Real estate ETFs
- High-income ETFs
- Some alternative-income funds
Monthly income can be convenient, but investors should still examine where the distribution comes from.
A high monthly payment does not automatically mean the underlying investment is producing a high sustainable return.
Why Do Some ETFs Pay Monthly?
Some funds hold investments that generate income regularly, while others are specifically structured around income generation. Bond ETFs are one example where monthly distributions are common.
Are Monthly Dividend ETFs Better Than Quarterly ETFs?
Not automatically. A monthly dividend ETF and a quarterly dividend ETF should be compared based on:
- Total return
- Distribution yield
- Distribution consistency
- Fees
- Risk
- Holdings
- Strategy
- Tax treatment
The frequency of the payment is only one part of the picture.
ETF Dividend Yield Explained
ETF dividend yield helps investors understand how much annual income an ETF has distributed relative to its price.
A simplified calculation is:
Dividend Yield = Annual Dividend or Distribution ÷ ETF Price × 100
For example, if an ETF distributes $4 per year and its price is $100: $4 ÷ $100 × 100 = 4%
That does not mean the investor is guaranteed a 4% return. The ETF’s price can rise or fall, and future distributions can change.
But investors should be careful when comparing yields.
Different websites may calculate yield differently.
Some may use:
- Trailing 12-month distributions
- Forward distributions
- SEC yield for bond funds
- Estimated annualized distributions
Therefore, always check how the yield was calculated.
Why Does ETF Dividend Yield Change?
ETF dividend yield can change because:
- The ETF price changes.
- The fund’s distributions change.
- Underlying companies change their dividends.
- Interest income changes.
- The fund changes its holdings or strategy.
Therefore, never assume that today’s yield will remain the same indefinitely.
ETF Dividend Yield vs. Distribution Yield
This distinction is important. The term “dividend yield” is commonly used by investors, but ETFs can distribute more than traditional stock dividends. The terms dividend yield and distribution yield are sometimes used interchangeably, but they can represent different calculations. Distribution yield focuses on the amount an ETF has distributed. Dividend yield may be used more broadly for income from dividend-paying securities.
For income ETFs, understanding the calculation is important because a large distribution rate can sometimes include sources that are not ordinary dividends.
An ETF’s distribution can include:
- Dividends
- Interest
- Capital gains
- Return of capital
- Other income
Therefore, investors should look at the fund’s official distribution information to understand what they are actually receiving.
Is a High Distribution Yield Better?
Not necessarily. A very high distribution rate can sometimes indicate a more aggressive or specialized investment strategy. A fund paying a 10% distribution is not automatically better than a fund paying 3%.
The higher-distribution ETF could have:
- Higher volatility
- Higher expenses
- Lower price appreciation
- Greater downside risk
- More variable distributions
This is why yield should be considered alongside total return and risk.
Why a High ETF Yield Can Be Misleading
A high yield may look attractive, but it does not tell you everything about an ETF.
Suppose:
- ETF A yields 3%
- ETF B yields 10%
It may be tempting to choose ETF B.
But what if ETF B has:
- Higher risk
- Higher expenses
- Falling NAV
- Large price volatility
- Unsustainable distributions
In that situation, the 10% yield may not provide the better investment result.
Always compare income + price performance + risk + expenses.
ETF Dividend History
ETF dividend history shows how much a fund has distributed over time.
Investors can use dividend history to examine:
- Distribution consistency
- Payment frequency
- Distribution increases
- Distribution reductions
- Unusually large payments
- Historical yield
- Changes in the fund’s strategy
However, historical distributions do not guarantee future distributions.
What Should You Look for in ETF Dividend History?
Don’t look only for the biggest payment.
Instead, ask:
- How frequently does the ETF pay?
- Has the distribution been consistent?
- Have distributions increased or decreased?
- Are large payments unusual?
- What is the distribution made up of?
- How has the ETF’s NAV performed?
- What has the fund’s total return been?
VYM Dividend History
VYM, the Vanguard High Dividend Yield ETF, is commonly researched by investors looking for dividend-focused exposure. When reviewing VYM dividend history, look at the fund’s historical distributions rather than focusing only on the latest payment.
VYM,Vanguard High Dividend Yield ETF, commonly known by its ticker VYM, focuses on U.S. companies with relatively high dividend yields.
Investors researching VYM dividend history should look beyond one recent payment.
Useful things to examine include:
- Quarterly distribution amounts
- Annual distributions
- Distribution growth
- Dividend yield
- Expense ratio
- Portfolio holdings
- Total return
VYM is often considered by investors
VYM Dividend Schedule
VYM has historically followed a quarterly distribution schedule. Investors researching VYM should check the latest official fund information for:
- Distribution amount
- Ex-dividend date
- Record date
- Payment date
- Annual distribution
- Distribution yield
VYM Dividend Yield
VYM’s dividend yield changes over time because both its distributions and market price can change. A higher yield caused by a falling share price is not necessarily a positive development.
VYM Dividend Growth
Historical dividend growth can be useful, but investors should also consider:
- Portfolio composition
- Sector exposure
- Expense ratio
- Total return
- Valuation
- Market conditions
What Should You Look for in VYM Dividend History?
Instead of asking only, “What is the latest VYM dividend?” consider:
- Has the distribution generally grown?
- How consistent have payments been?
- What is the current yield?
- How has the ETF’s total return performed?
- How diversified is the portfolio?
- What are the fund’s expenses?
This provides a much better picture than looking at one dividend payment.
TLT Dividend History
TLT, the iShares 20+ Year Treasury Bond ETF, is different from a traditional stock dividend ETF. It invests primarily in long-term U.S. Treasury bonds, so its distributions are largely connected to the interest generated by those bonds. Investors searching for TLT dividend history should therefore think about TLT as an income-producing bond ETF rather than a conventional dividend-stock ETF.
How TLT Distributions Work
TLT receives interest from the Treasury securities in its portfolio. That income can then contribute to distributions made to shareholders. The amount distributed can change over time because the fund’s portfolio changes and because bonds mature, are replaced, or are acquired at different yields.
Why Can TLT Distributions Change?
TLT’s distribution can change because of factors affecting the income generated by its bond portfolio, its holdings, and fund expenses. Importantly, TLT also has significant interest-rate risk. A high distribution does not remove the possibility that the ETF’s share price can fall when interest rates rise.
TLT Dividend Yield
When looking at TLT’s yield, remember that the quoted yield can change as:
- Bond income changes
- The ETF’s market price changes
- Treasury yields change
- Portfolio holdings change
- Distribution amounts change
Therefore, today’s TLT yield should not be treated as a guaranteed future income rate.
TLT and Interest Rate Risk
This is one of the most important things to understand about TLT. TLT holds long-duration Treasury bonds. Long-term bonds can be particularly sensitive to changes in interest rates. When interest rates rise, existing long-term bonds can become less attractive compared with newly issued bonds. Their market prices can therefore decline. When rates fall, long-duration bonds can benefit from price appreciation.
This means TLT investors need to consider both: “Income + bond price movement” rather than focusing only on the monthly distribution.
TLT Dividend vs Total Return
Suppose TLT pays attractive monthly distributions but its market price falls significantly. The investor’s total return could still be negative.
This is why TLT dividend history should be studied together with:
- TLT price history
- Total return
- Treasury yields
- Interest-rate expectations
- Distribution history
Is TLT a Dividend ETF?
Technically, TLT is an ETF that invests in Treasury bonds rather than a traditional dividend-stock ETF. It provides income from its bond holdings, which is distributed to shareholders. So if your goal is income, TLT may be relevant, but it should not be evaluated in exactly the same way as a dividend-stock ETF such as VYM.
TSPY Dividend History
TSPY is another ETF investors may research when looking for income and distribution history. When reviewing TSPY dividend history, do not focus only on the size of its latest distribution.
Look at:
- Distribution frequency
- Historical distribution amounts
- Distribution yield
- Fund strategy
- Expense ratio
- NAV performance
- Total return
- Risk level
Some high-income ETF strategies can generate large distributions while also exposing investors to greater risks. That is why distribution history needs to be viewed together with performance.
ETF Dividend Calendar and Important Dates
Understanding the ETF dividend calendar can help investors know when an ETF declares a distribution, when they must own shares to receive it, and when the money is actually paid. ETF distributions generally involve four important dates:
Declaration Date
The declaration date is when the ETF issuer or fund announces an upcoming distribution. The announcement may include the distribution amount, ex-dividend date, record date, and payment date. The distribution amount can vary from one period to another because ETFs typically pass through income generated by their underlying holdings.
Ex-Dividend Date
The ex-dividend date is one of the most important dates for ETF investors. If you purchase the ETF on or after the ex-dividend date, you generally will not receive that particular upcoming distribution. If you own the ETF before the ex-dividend date and meet the fund’s eligibility requirements, you generally qualify for the distribution. Investors should not assume that buying an ETF immediately before the ex-dividend date creates free income. ETF prices can adjust downward around the ex-dividend date to reflect the distribution, while taxes and transaction costs may also affect the overall result.
Record Date
The record date is the date the fund uses to identify shareholders entitled to receive the distribution. For investors, the practical date to watch is usually the ex-dividend date, because the trading and settlement rules determine whether a purchase qualifies for the distribution.
Payment Date
The payment date is when the ETF distribution is actually paid to eligible shareholders. Depending on the brokerage and account type, the distribution may appear as cash in the account or be automatically reinvested if the investor has a dividend reinvestment option enabled.
ETF Dividend Calendar: Why These Dates Matter
These dates are especially important when you are planning to buy or sell an ETF around a distribution. Before trading, check the fund’s latest distribution announcement because dates and distribution amounts can change from one period to the next. Also remember that an ETF’s distribution yield is only one part of its potential return. Investors should consider total return, share-price performance, expense ratio, tax implications, and the fund’s underlying holdings rather than choosing an ETF solely because it has a high dividend or distribution yield.
Should You Buy an ETF Just Before Its Dividend?
Usually, buying an ETF immediately before a distribution simply to “capture” the dividend is not a free-money strategy. The ETF’s price or NAV can adjust when the distribution is made. You should evaluate the investment based on its total return, risk, costs, and suitability, rather than trying to collect a distribution without considering the corresponding price adjustment.
Also Read: VT ETF
ETF Dividends vs Stock Dividends
Owning a dividend stock means receiving income directly from one company.
Owning a dividend ETF means you own a fund containing multiple securities.
Individual Dividend Stock
Potential advantages:
- Direct ownership of one company
- Potential dividend growth
- Potential capital appreciation
Potential disadvantages:
- Company-specific risk
- Dividend cuts
- Greater concentration
Dividend ETF
Potential advantages:
- Diversification
- Easier portfolio management
- Exposure to many dividend-paying companies
- Potential regular income
Potential disadvantages:
- Fund expenses
- Less control over individual holdings
- Distributions can change
- ETF price can decline
ETF Dividends vs Interest Income
Not all ETF income comes from dividends. A stock ETF may receive dividends from companies. A bond ETF generally receives interest from bonds.
For example:
Stock ETF → dividends from stocks
Bond ETF → interest from bonds
The tax treatment can also differ depending on the type of income and the investor’s tax situation.
Are ETF Dividends Taxable?
In a taxable investment account, ETF distributions may be taxable. However, the tax treatment depends on the type of distribution and your individual circumstances.
Distributions may potentially include:
- Qualified dividends
- Ordinary dividends
- Capital gains
- Return of capital
- Interest income
The tax treatment can vary significantly between these categories. If you are investing in ETFs in the United States, review the fund’s tax documents and consider speaking with a qualified tax professional about your situation.
Are ETF Dividends Taxed as Ordinary Income?
Not necessarily. Some distributions may receive different tax treatment depending on their classification. For example, qualified dividends may be taxed differently from ordinary income when applicable requirements are met.
The important lesson is: Do not assume every ETF distribution is taxed the same way.
Should You Reinvest ETF Dividends?
Investors generally have two broad choices:
Take the Cash
You receive the distribution as cash. This may be useful if your goal is investment income.
Reinvest the Distribution
You use the distribution to purchase additional ETF shares. This can help compound your investment over time. For long-term investors who do not need the cash, reinvestment can be a useful strategy. However, the right choice depends on your goals, account type, taxes, and overall financial plan.
How to Choose a Dividend ETF
Choosing a dividend ETF should involve more than searching for the fund with the highest yield. A high distribution yield can sometimes come from falling share prices, unusually large distributions, or an income strategy that carries additional risk. Before investing, compare the ETF’s income, total return, costs, holdings, strategy, liquidity, and risk profile.
1. Distribution Yield
Check the ETF’s recent distribution yield, but don’t treat it as a guarantee of future income. Distribution yields can change as the ETF’s distributions and market price change. A very high yield may also indicate greater exposure to certain sectors, declining asset prices, option strategies, or other risks. Compare the yield with similar ETFs rather than judging it in isolation.
2. Total Return
Look at total return, not just dividend income. Total return combines distributions with changes in the ETF’s share price. An ETF paying a high distribution may still produce a weaker overall result if its share price declines significantly.
When comparing funds, consider total return over multiple periods, such as:
- 1 year
- 3 years
- 5 years
- 10 years, when available
Past performance does not guarantee future results, but it can provide useful historical context.
3. Expense Ratio and Other Costs
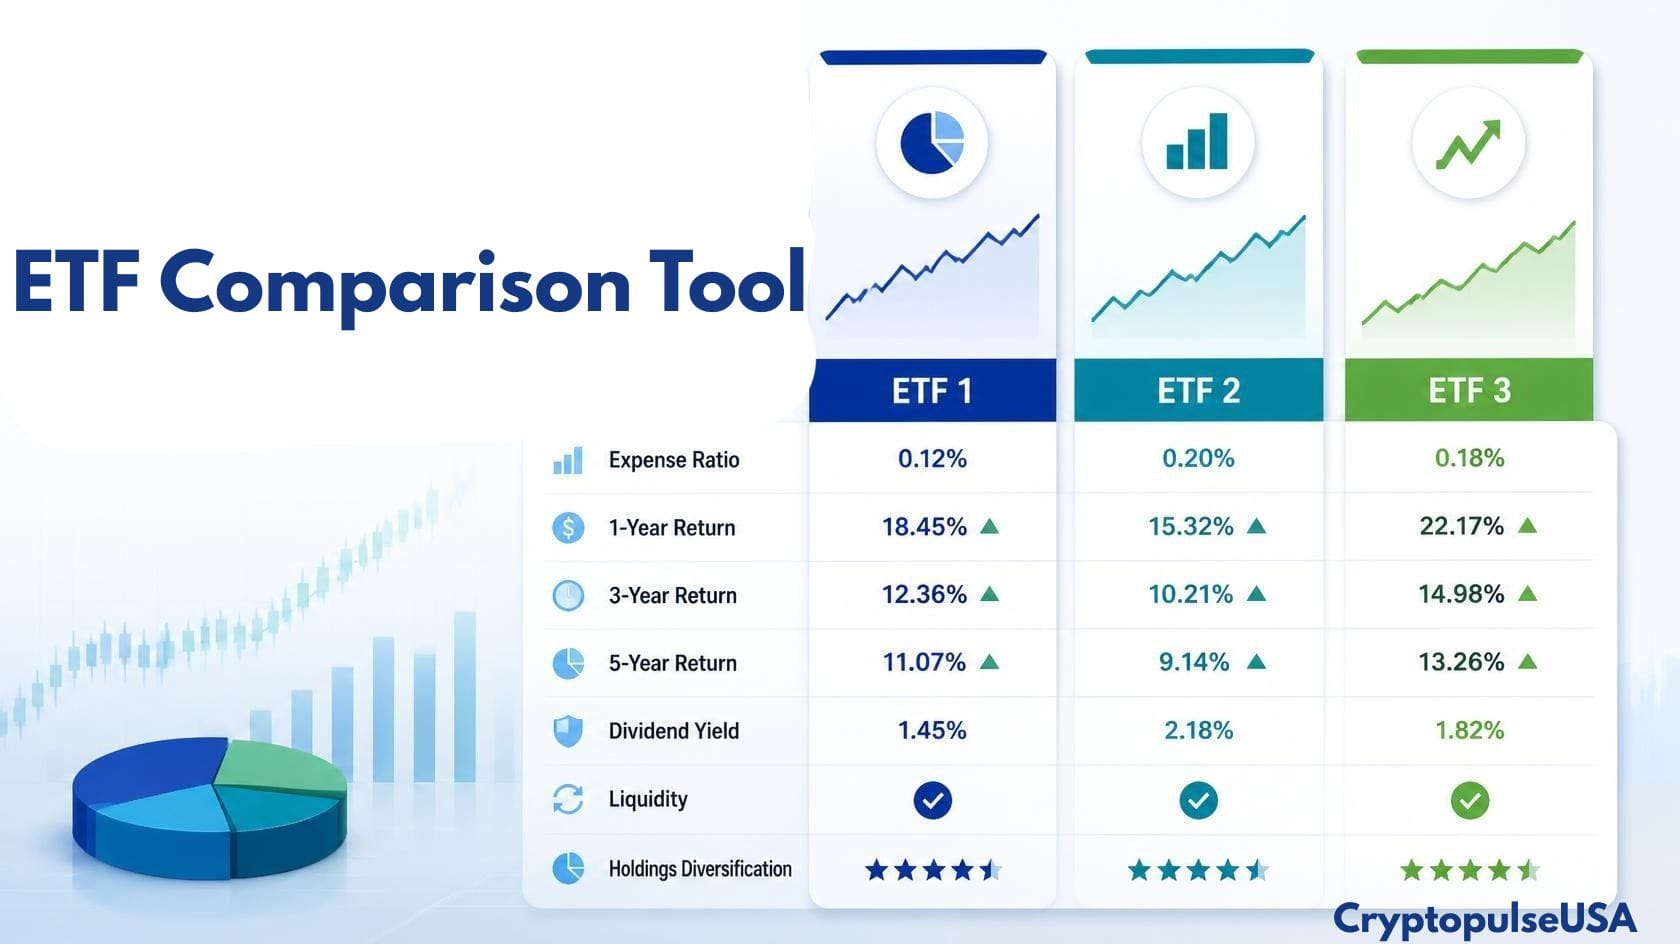
The expense ratio shows the annual operating expenses charged by the fund as a percentage of assets. Lower costs can help preserve long-term returns, but the cheapest ETF is not automatically the best choice.
Also consider:
- Bid-ask spread
- Trading commissions, if applicable
- Tracking difference
- Portfolio turnover
- Any other fund-specific expenses
For income-focused investors, even relatively small recurring costs can matter over long holding periods.
4. Distribution History
Review the ETF’s historical distribution record.
Look for whether distributions have been:
- Stable
- Growing
- Declining
- Highly variable
Don’t assume that a history of increasing distributions means the trend will continue. Dividend payments can change when companies reduce dividends, portfolio holdings change, or the ETF’s investment strategy produces different levels of income. Also check how frequently the ETF distributes income, such as monthly, quarterly, or annually.
5. Portfolio Holdings
Examine what the ETF actually owns.
Check its:
- Top holdings
- Number of holdings
- Sector allocation
- Industry exposure
- Geographic exposure
- Market-cap exposure
- Weight of the largest positions
Two ETFs can have similar dividend yields while having very different portfolios and risk levels. For example, a dividend ETF concentrated in financial stocks may behave very differently from a diversified fund holding companies across healthcare, consumer staples, industrials, technology, and other sectors.
6. Investment Strategy
Understand how the ETF generates income. A traditional dividend ETF may focus on companies with relatively strong dividend characteristics, while other income ETFs may use different approaches. For example, a covered-call ETF can generate option-premium income by selling call options against some or all of its portfolio. This can create higher distributions, but it can also limit some upside potential and introduce additional strategy-specific risks.
Other ETFs may focus on:
- Dividend growth
- High dividend yield
- Dividend quality
- Value stocks
- Preferred stocks
- Bonds and other income-producing assets
- Covered-call strategies
Always read the fund’s objective and methodology before comparing yields.
7. Dividend Quality and Sustainability
Don’t look only at how much a company or ETF currently pays. Consider whether the underlying income appears sustainable.
For equity dividend ETFs, examine factors such as:
- Company profitability
- Free cash flow
- Dividend payout ratios
- Balance-sheet strength
- Dividend growth history
- Earnings stability
An ETF that owns financially stronger companies may have a different risk profile from one that simply selects stocks based primarily on high current yields.
8. Liquidity and Bid-Ask Spread
Liquidity matters when buying or selling an ETF.
Look at:
- Average trading volume
- Assets under management
- Bid-ask spread
- Trading activity during normal market hours
A highly liquid ETF with a tight spread can generally be easier and less costly to trade than a thinly traded fund. Don’t judge liquidity by trading volume alone. The bid-ask spread is also important because it represents a potential trading cost.
9. Risk and Volatility
Every dividend ETF carries investment risk. A dividend payment does not protect investors from losses in the underlying assets.
Depending on the ETF, risks may include:
- Equity risk — stock prices can decline.
- Interest-rate risk — particularly important for bond and preferred-stock ETFs.
- Credit risk — issuers may experience financial problems or default.
- Sector concentration risk — heavy exposure to one sector can increase volatility.
- Market risk — the entire market can fall.
- Option risk — relevant to covered-call and other options-based ETFs.
- Currency risk — relevant to funds holding foreign assets.
- Concentration risk — a small number of holdings may account for a large percentage of the portfolio.
Review the fund’s prospectus and risk disclosures before investing.
10. Tax Considerations
Taxes can affect the amount of income you actually keep. For U.S. investors, the tax treatment of ETF distributions can vary depending on whether distributions are classified as qualified dividends, ordinary income, capital gains, or return of capital. Don’t assume that every distribution from a dividend ETF receives the same tax treatment. Investors should review the fund’s tax information and consider their own account type and tax situation. Tax rules can also change, so consult a qualified tax professional when necessary.
11. Benchmark and Index Methodology
If the ETF tracks an index, understand how that index selects and weights its holdings.
Two dividend ETFs may use different rules for:
- Dividend yield
- Dividend growth
- Dividend history
- Company quality
- Market capitalization
- Sector limits
- Rebalancing frequency
- Position weighting
Understanding the methodology can help explain why two funds with similar objectives can produce different results.
12. Assets Under Management and Fund Size
Consider the ETF’s assets under management (AUM) and fund history. A larger fund may have greater trading liquidity and an established operating history, but fund size alone should not determine your decision. A smaller or newer ETF can still be appropriate if its strategy, costs, liquidity, and holdings fit your objectives.
13. Match the ETF to Your Investment Goal
Finally, choose the ETF based on what you actually need from your portfolio.
For example:
- Current income: You may prioritize distribution yield and income consistency.
- Long-term dividend growth: You may prioritize companies with sustainable and growing dividends.
- Capital appreciation: You may prefer an ETF that balances dividend income with growth potential.
- Lower volatility: You may look for diversified holdings and a strategy designed to reduce portfolio risk.
- Options-based income: You may consider covered-call ETFs while understanding their trade-offs.
Dividend ETF Selection Checklist
Before investing, ask:
- What is the ETF’s current distribution yield?
- What has its total return been over different periods?
- What is the expense ratio?
- How consistent have its distributions been?
- What companies or assets does it hold?
- How concentrated is the portfolio?
- What strategy does the ETF use?
- How liquid is the fund?
- What are its major risks?
- How might its distributions be taxed?
- What benchmark or index does it follow?
- Does the ETF match my investment objective and risk tolerance?
The best dividend ETF is not necessarily the one with the highest yield. A stronger choice is usually the fund whose income, costs, diversification, strategy, risk, and total-return potential align with your investment goals.
Also Read: VFH ETF
High-Yield Dividend ETFs
High-yield ETFs can be attractive for investors seeking income.
But a high yield should always trigger another question: Why is the yield so high?
A high yield may result from:
- Falling share price
- High underlying income
- Options strategies
- High-risk securities
- Special distributions
- Return of capital
Therefore, investors should investigate the source of the distribution before assuming the yield is sustainable.
Return of Capital and ETF Distributions
Some ETF distributions may include return of capital. Return of capital is different from ordinary dividend income. It can represent a return of some of your invested capital rather than income generated by the portfolio. This is important because a high distribution can sometimes make an ETF appear more profitable than it actually is. Always check the fund’s distribution classifications and tax documents.
ETF Dividends and Total Return
One of the biggest mistakes investors make is focusing only on dividends.
A better measure is total return. Total return generally considers: Price change + distributions
For example, imagine:
- ETF price falls 5%
- Distributions equal 6%
The investor’s total return would not simply be “6% income.” The price decline also matters. This is why dividend yield should never be viewed in isolation.
ETF Liquidity and Bid-Ask Spread
Liquidity is another factor investors sometimes overlook. The bid-ask spread is the difference between the price buyers are willing to pay and the price sellers are asking. A very wide spread can increase trading costs.
When comparing similar ETFs, investors may want to consider:
- Average trading volume
- Bid-ask spread
- Assets under management
- Fund size
A high distribution does not compensate for every possible trading or liquidity problem.
ETF Expense Ratio and Dividends
Every ETF has operating expenses. The expense ratio represents the annual operating costs charged by the fund. For example, if two similar ETFs provide similar performance but one has significantly higher expenses, the lower-cost ETF may have an advantage over the long term.
Remember:
Yield is not the same as net return. Always consider expenses when comparing income ETFs.
Weekly vs Monthly vs Quarterly Dividend ETFs
There is no universally best payment frequency.
| Payment Frequency | Potential Benefit | Important Consideration |
|---|---|---|
| Weekly | Very frequent cash flow | May use specialized strategies |
| Monthly | Regular income | Distribution can change |
| Quarterly | Common for stock ETFs | Longer wait between payments |
| Annual | Simple distribution schedule | Less frequent cash flow |
Choose based on your investment goals rather than frequency alone.
What Makes a Dividend ETF “Best”?
There is no single best dividend ETF for everyone. The right ETF depends on what you want from your portfolio.
For example: Income-focused investor: May prioritize distribution income.
Long-term growth investor: May prioritize total return and dividend growth.
Conservative investor: May prioritize diversification and lower volatility.
Bond investor: May focus on income and interest-rate risk.
Taxable-account investor: May pay closer attention to distribution tax treatment.
The best choice is therefore the ETF that fits your goals and risk tolerance—not simply the ETF with the highest yield.
ETF Dividend Income Example
Suppose you invest $10,000 in an ETF with a hypothetical 4% annual distribution rate.
A simplified estimate would be: $10,000 × 4% = $400 per year
That could equal roughly: $400 ÷ 12 = $33.33 per month
But this is only an illustration. ETF distributions are not guaranteed, and the actual amount can change. The ETF’s price can also rise or fall.
Common ETF Dividend Mistakes
Dividend ETFs can provide regular distributions, but investors can make costly mistakes by focusing only on how much income a fund currently pays. A better approach is to evaluate the ETF’s total return, distribution sustainability, costs, taxes, holdings, and risk.
Here are some common mistakes to avoid.
Mistake 1: Choosing the Highest Yield
A high distribution yield does not automatically make an ETF a better investment. An unusually high yield can result from a falling share price, a temporary distribution, or a strategy designed to generate substantial income while accepting additional risks. Instead of choosing an ETF based solely on yield, compare its total return, distribution history, portfolio holdings, strategy, and risk with similar funds.
Mistake 2: Ignoring Total Return
Focusing only on distributions can give you an incomplete picture of an ETF’s performance. Total return considers both the income received and changes in the ETF’s market value. An ETF with a high distribution may still produce a weaker overall result if its share price declines substantially. When comparing dividend ETFs, look at total returns over several time periods rather than focusing on the latest distribution.
Mistake 3: Treating ETF Distributions as Guaranteed Income
ETF distributions are not guaranteed. For equity dividend ETFs, the underlying companies can reduce or eliminate their dividends. The ETF’s distribution can therefore change over time. Income-focused ETFs using options or other strategies can also have distributions that vary from one period to another. Investors should treat distributions as variable investment income rather than a guaranteed paycheck.
Mistake 4: Ignoring Expenses and Trading Costs
Even a strong dividend strategy can be affected by costs.
Before investing, check the ETF’s:
- Expense ratio
- Bid-ask spread
- Trading costs
- Portfolio turnover
- Tracking difference
A lower-cost ETF is not automatically better, but unnecessary costs can reduce long-term returns.
Mistake 5: Ignoring Taxes
Not all ETF distributions necessarily receive the same tax treatment. Depending on the fund and the investor’s circumstances, distributions may include qualified dividends, ordinary income, capital gains, or return of capital. Tax treatment can also differ depending on whether the ETF is held in a taxable brokerage account or a tax-advantaged account. Investors should review the fund’s tax documents and consider their own tax situation before making an investment decision.
Mistake 6: Buying Before the Ex-Dividend Date Just to Receive the Distribution
Some investors assume they can buy an ETF immediately before the ex-dividend date, collect the distribution, and make an easy profit. That generally does not work. All else equal, when an ETF goes ex-distribution, its market price can adjust downward by approximately the amount of the distribution. The exact market-price movement can differ because ETF prices also respond to normal market conditions.
Receiving a distribution does not automatically create additional wealth. Investors should evaluate the ETF based on total return and after-tax results, rather than trying to capture a distribution simply because it is about to be paid.
Mistake 7: Assuming More Frequent Payments Are Better
A monthly or weekly distribution schedule can look attractive, but payment frequency does not by itself determine investment performance. A fund paying weekly does not automatically generate more income than a comparable fund paying monthly or quarterly. What matters more is the ETF’s underlying assets, distribution policy, total return, costs, and risk. Also check whether a fund’s frequent distributions are being generated from dividends, interest, option premiums, capital gains, or other sources.
Mistake 8: Ignoring Portfolio Concentration
A dividend ETF may appear diversified while still having significant exposure to a particular sector or a relatively small number of companies.
Check the ETF’s:
- Top holdings
- Sector weights
- Industry exposure
- Geographic exposure
- Number of holdings
- Weight of its largest positions
Concentration can increase risk if a particular sector or group of companies performs poorly.
Mistake 9: Confusing Dividend Yield With Dividend Growth
A high current yield and strong dividend growth are not the same thing. One ETF may focus on companies offering higher current income, while another may prioritize companies with a history of increasing dividends. If your goal is long-term income growth, examine distribution growth and the quality of the underlying companies, rather than focusing only on today’s yield.
Mistake 10: Ignoring the ETF’s Investment Strategy
Not every income ETF generates distributions in the same way. A traditional dividend ETF may own dividend-paying stocks, while a covered-call ETF may generate significant income through option premiums. These strategies can have very different risk, return, volatility, and upside characteristics. Always understand how an ETF attempts to generate income before comparing its yield with another fund.
Mistake 11: Ignoring Risk Because an ETF Pays Dividends
Receiving regular distributions does not protect you from losses. A dividend ETF can decline significantly when its underlying stocks fall. Bond and other income-oriented ETFs can also face risks such as interest-rate, credit, liquidity, and market risk.
Before investing, consider whether the ETF’s volatility and potential drawdowns fit your risk tolerance and investment time horizon.
Mistake 12: Focusing Only on the Distribution Instead of the Investment Goal
The right ETF depends on what you are trying to accomplish. An investor seeking current income may prioritize a different ETF from someone seeking long-term dividend growth or a combination of income and capital appreciation.
Before choosing a fund, consider:
- Your investment objective
- Required income
- Time horizon
- Risk tolerance
- Tax situation
- Diversification needs
- Total-return expectations
How to Avoid ETF Dividend Mistakes
A simple way to evaluate a dividend ETF is to look beyond its headline yield. Review the distribution history, total return, expense ratio, portfolio holdings, strategy, liquidity, tax treatment, and major risks. The goal is not necessarily to find the ETF that pays the most. It is to find an ETF whose income characteristics, growth potential, costs, and risk profile fit your overall investment plan.
FAQs About ETF and Dividends
Do all ETFs pay dividends?
No. Some ETFs pay regular distributions while others may pay little or nothing.
How often do ETFs pay dividends?
ETFs may distribute income weekly, monthly, quarterly, semiannually, or annually, depending on the fund.
What is a weekly dividend ETF?
A weekly dividend ETF is an ETF designed to provide distributions on a weekly basis or use an income strategy that supports frequent distributions.
Are ETF dividends taxable?
ETF distributions in taxable accounts can be taxable, but the treatment depends on the type of distribution and the investor’s circumstances.
Can ETF dividends change?
Yes. ETF distributions can increase, decrease, or vary significantly depending on the fund’s holdings and strategy.
Is a high ETF dividend yield better?
Not necessarily. A high yield may come with higher risk, falling prices, higher expenses, or distributions that are not entirely ordinary income.
What is the difference between ETF dividends and ETF distributions?
Dividends are income paid by companies. ETF distributions are payments made by an ETF and can contain dividends, interest, capital gains, return of capital, or other amounts.
What is VYM dividend history?
VYM dividend history refers to the record of distributions paid by the Vanguard High Dividend Yield ETF over time. Investors can use it to study distribution trends, but should also consider total return and risk.
What is TLT dividend history?
TLT dividend history refers to the historical distributions of the iShares 20+ Year Treasury Bond ETF. Because TLT invests in long-term Treasury bonds, its distributions are primarily related to income generated by those bonds.
What is TSPY dividend history?
TSPY dividend history shows the ETF’s previous distributions. Investors should examine the distribution schedule, yield, strategy, expenses, and total return rather than focusing only on individual payments.
Final Thoughts on ETF and Dividends
Understanding ETF and dividends is about much more than finding the ETF with the biggest yield.
Before investing, look at:
- Distribution history
- Distribution yield
- Total return
- Expense ratio
- Portfolio holdings
- Distribution frequency
- Tax treatment
- Liquidity
- Investment strategy
- Risk
Weekly dividend ETFs can provide frequent cash flow, while monthly and quarterly dividend ETFs may offer different approaches to income. Funds such as VYM and TLT also show why investors need to understand what is actually generating an ETF’s distributions. VYM is focused on dividend-paying stocks, while TLT generates income from long-term Treasury bonds.
The most important rule is simple: Do not judge an ETF only by its dividend yield.
Look at the complete picture “income, total return, costs, risk, and long-term goals” before making an investment decision.
This article is for educational and informational purposes only. It is not financial, investment, tax, or legal advice. ETF distributions, prices, yields, and performance can change, and past performance does not guarantee future results.



Leave a Reply